
About Bridging Loans Australia
Bridging Loans Australia is a specialist brokerage that arranges short-term, property-secured finance. It is the only thing we do. We are based in Bondi Junction in Sydney and arrange facilities across Australia, with most of the process handled remotely.
Most brokerages carry bridging finance as one product among forty. We carry it as the whole business, which means the questions we ask on a first call are the ones that actually determine whether a facility can be written: what the security is worth, what is already secured against it, what repays the loan, and when.
What we do, and what we do not do
Being specific about the second half of that is more useful to you than any claim we could make about the first.
We arrange
-
Residential bridging loans, where a home is being bought before the existing one settles
-
Commercial bridging loans secured by commercial or mixed-use property
-
Second mortgage facilities sitting behind an existing first mortgage, for business and investment purposes
-
Settlement funding where a transaction has a date that conventional approval will not meet
-
Buy before you sell structures, including purchases at auction
We do not arrange
-
Unsecured lending of any kind. Every facility we arrange is secured by real property.
-
Standard home loans, refinances or investment loans on ordinary timeframes. If that is what you need, a general mortgage broker will price it better than we will.
-
Consumer-purpose second mortgages. There is very little appetite for these in the market and we would rather say so than take you through an application that ends the same way.
-
Facilities without an identified exit. If there is no sale, no refinance and no realisation event that repays the loan, the honest answer is that bridging finance is the wrong tool, and postponing that answer costs you money.
Why the second list matters. A short-term facility that cannot be repaid on time does not quietly roll over. It accrues at a short-term rate against a property you own. The single most useful thing a bridging specialist does is decline the transactions that were never going to work, early, while you still have other options.

Jake
Director:
Structures and submits every scenario, and is the person you speak to about whether a deal is workable. Years in finance, prior firms, any accreditation worth naming
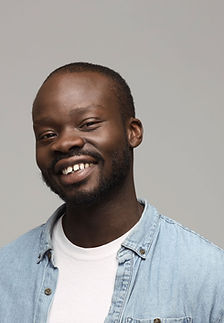
Dan
BDM:
Lender relationships and first-response assessment. One line on background

Ash
IT Developer
Maintains the site and the systems behind it.
How we are paid
Worth stating plainly, because most brokerages leave it to a footnote.
-
We are paid a commission by the lender when a facility settles. Confirm: is this the case for every lender on your panel, or do some scenarios carry a broker fee paid by the borrower? If the latter, say so here and say when it applies.
-
Commission does not increase the rate you are quoted. Only publish this line if it is true across your panel. Delete it if any lender prices differently for broker-introduced business.
-
The commission we receive is disclosed to you in writing before you commit to anything, as it must be.
-
We do not receive a benefit for placing you with one lender over another. Confirm before publishing. If commission rates differ across your panel, this line needs rewording, not deleting.
Our credentials and how to check them
This paragraph needs the exact disclosure your compliance adviser signs off on. It should name the licensed entity, the Australian Credit Licence number, and, if you operate as a credit representative, your credit representative number and the licensee's name. Whatever wording you settle on, use it word for word in the site footer as well, so the two agree.
Anyone can check a credit licence themselves, and you should. Credit licensees and credit representatives are listed on ASIC's professional registers, which are free and public, and the record will show the licence number, the entity that holds it and whether it is currently in force. If a finance business will not tell you its licence number, that is the end of the conversation.
We are also required to be a member of an external dispute resolution scheme, which in Australia is the Australian Financial Complaints Authority. That means if something goes wrong and we cannot resolve it with you directly, you have somewhere independent to take it.
How a scenario gets assessed
Every enquiry runs through the same five questions, in this order.
-
What is the security worth, and what is already against it? This sets the ceiling on everything that follows.
-
What is the loan to value ratio? Both against the individual security and, where two properties are involved, against the combined position.
-
What repays the loan? A sale, a refinance, a settlement, a realisation. It has to be specific and it has to be dated.
-
How likely is that exit to happen on time? Assessed on the evidence, not the intention. An unlisted property with no agent appointed is not a dated exit.
-
What happens if it is late? Because sometimes it is, and the cost of that is a number you should see before you sign, not after.
Assessment on assets and exit rather than on income is the fundamental difference between this and bank lending, and it is why a self-employed borrower with two years of unlodged returns and substantial equity can be straightforward here and impossible elsewhere. It is explained in full in how bridging loans work, and the terminology is defined in our glossary.
Who we work with
Eligibility is set out in full on who we help. In summary, we work with:
-
Property investors holding equity that is not accessible on bank timeframes
-
Developers needing site acquisition, residual stock or completion funding
-
Business owners using property equity for a business purpose
-
Self-employed borrowers whose income is real but does not present the way a bank needs it to
-
Borrowers declined elsewhere, where the reason for the decline is understood and there is a route past it
-
Homeowners buying before selling, which is the most common scenario we see
-
Where we lend
Nationally. Our lender panel operates across every state and territory, and we have written detail on the local rules that change how a transaction runs in Sydney, Melbourne, Brisbane, Perth and Adelaide, with the national picture on our locations page.
Security in regional centres and larger coastal markets is generally acceptable. The further a property sits from a market where comparable sales are readily available, the more conservative a lender's position tends to be, and in genuinely remote locations some lenders will not take the security at all. Where a property sits on that spectrum is worth establishing at the first call rather than after a valuation.
What we will tell you that you may not want to hear
Bridging finance is a timing tool. It is priced above bank lending because it is faster, shorter and assessed differently, and it is worth that premium when it buys you a transaction you would otherwise lose. It is not worth it when the underlying problem is that a purchase is unaffordable, or when a property has been on the market for eight months without an offer.
If your scenario is one where waiting, renegotiating a settlement date or going back to your existing lender is the better answer, we will say so. It costs us a transaction and saves you considerably more.
Speak to a specialist
Tell us the property, what is owed against it, what you are trying to do and by when. That is enough for an initial view on whether a facility is workable and roughly what it would cost.
Contact us to discuss a scenario, use the bridging loan calculator to model the numbers first, or read the frequently asked questions.